The Life Insurance Corporation of India (LIC) introduced three new insurance plans in October 2026, expanding its offerings in retirement planning and health protection. The new plans include LIC New Jeevan Dhara-II (Plan 892), LIC Health Shield (Plan 907), and LIC New Cancer Cover (Plan 908). They went on sale from 19 October 2026.
These plans address three different financial needs: guaranteed retirement income, financial support during hospitalisation and major surgeries, and financial protection against cancer. They are also important additions to the LIC product portfolio for insurance agents who want to serve customers with different protection and retirement requirements.
For insurance professionals, understanding these differences is important when explaining the products to customers and building a comprehensive LIC Agent Guide.
In this article, we explain LIC’s new plans for 2026, including their features, eligibility, benefits, policy terms, and what LIC agents should know before recommending them.
The information is based on the LIC press release (13 Oct 2026).
LIC New Plans 2026 at a Glance:
LIC announced the three new plans through a press release dated 13 October 2026, issued in Mumbai. The plans were launched by R. Doraiswamy, CEO and Managing Director of LIC, and became available for purchase from 19 October 2026.
Here is a quick comparison of the three new LIC insurance plans:
| Plan name | Plan number | UIN | Type | Entry age | Policy term | Best for |
|---|---|---|---|---|---|---|
| LIC New Jeevan Dhara-II | 892 | 512N398V01 | Deferred annuity | 18 years onwards, subject to deferment and maximum entry age | Deferment period of 1–15 or 2–15 years, depending on premium mode | Retirement income |
| LIC Health Shield | 907 | 512N369V01 | Health insurance – pure risk | Principal insured: 18–65 years; children: 90 days–20 years | 15 years | Family hospital cash and surgical benefits |
| LIC New Cancer Cover | 908 | 512N370V01 | Health insurance – pure risk | 18–65 years | 10–15 years | Financial protection against cancer |
Each plan has a different purpose and target customer.
- LIC New Jeevan Dhara-II: Designed for people who want to arrange a regular income after a selected deferment period.
- LIC Health Shield: Designed for families seeking fixed financial benefits during hospitalisation and major surgeries.
- LIC New Cancer Cover: Designed for individuals who want financial support following an early-stage or major-stage cancer diagnosis.
LIC New Jeevan Dhara-II (Plan 892)
LIC New Jeevan Dhara-II is a non-participating, non-linked individual savings deferred annuity plan. It is designed for individuals who want to arrange a regular income for their retirement years.
A deferred annuity means that the customer invests in the plan first and starts receiving the annuity (pension) after a selected waiting period, known as the deferment period.
For example, someone purchasing the plan at an early age can choose to defer the annuity for a specified period. Once the deferment period ends, the annuity payments begin according to the selected option.
This arrangement can help individuals plan their future retirement income rather than waiting until retirement to think about regular financial support.
Key Features of LIC New Jeevan Dhara-II
The important features of LIC New Jeevan Dhara-II include:
1. Guaranteed annuity rates from day one
One of the notable features is the availability of guaranteed annuity rates from the beginning of the policy. This allows customers to understand the applicable annuity terms when purchasing the plan.
2. Single premium and regular premium options
Customers can choose between single-premium and regular-premium payment structures, depending on the available option and their financial preferences.
3. Single-life and joint-life options
The plan offers single-life as well as joint-life annuity options. A single-life option is intended for one annuitant, while a joint-life option can provide annuity benefits involving two individuals.
4. Top-up annuity facility
The top-up annuity facility provides an additional way to increase the annuity arrangement, subject to the applicable policy conditions.
5. Incentives for eligible customers
The plan provides incentives in connection with high-premium policies, existing LIC customers, and nominees of deceased LIC policyholders.
These features can make the product relevant to existing LIC customers who are looking for an additional retirement-income arrangement.
Eligibility for LIC New Jeevan Dhara-II
The eligibility conditions depend on the premium payment method and the selected deferment period.
| Particular | Eligibility |
|---|---|
| Minimum entry age | 18 years |
| Maximum entry age | Up to 65 or 70 years, subject to deferment |
| Minimum vesting age | 30 years |
| Maximum vesting age | 65 or 70 years |
| Deferment period – regular premium | 2–15 years |
| Deferment period – single premium | 1–15 years |
The entry age and vesting age must satisfy the conditions applicable to the selected option.
11 Annuity Options Under LIC New Jeevan Dhara-II
LIC New Jeevan Dhara-II (Plan 892) offers 11 annuity options under regular-premium and single-premium payment methods. Customers can choose between single-life and joint-life annuity options depending on their retirement income requirements and family preferences.
| Option No. | Single/Joint | What You Get |
|---|---|---|
| Option 1 | Single Life | Lifetime annuity without return of premium. |
| Option 2 | Single Life | Lifetime annuity with return of premium. |
| Option 3 | Single Life | 50% return of premium after attaining age 75 years. |
| Option 4 | Single Life | 100% return of premium after attaining age 75 years. |
| Option 5 | Single Life | 50% return of premium after attaining age 80 years. |
| Option 6 | Single Life | 100% return of premium after attaining age 80 years. |
| Option 7 | Single Life | 5% return of premium annually from age 76 to 95 years. |
| Option 8 | Joint Life | Lifetime annuity for two lives. |
| Option 9 | Joint Life | Lifetime annuity with return of premium. |
| Option 10 | Single Life | Lifetime annuity with return of purchase price (single premium). |
| Option 11 | Joint Life | Lifetime annuity with return of purchase price (single premium). |
Important points:
- Options 1–9 are available under regular-premium arrangements.
- Options 10–11 are available under single-premium arrangements.
- Under joint-life options, the secondary annuitant receives the annuity after the primary annuitant’s death, according to policy conditions.
- The selected annuity option cannot be changed later.
Minimum Annuity and Premium
LIC New Jeevan Dhara-II specifies minimum annuity amounts according to the payment frequency.
| Annuity payment frequency | Minimum annuity |
|---|---|
| Monthly | ₹1,000 |
| Quarterly | ₹3,000 |
| Half-yearly | ₹6,000 |
| Yearly | ₹12,000 |
The amount customers need to invest depends on their age, premium payment method, deferment period and selected annuity option.
Agents should use the latest official LIC sales illustration to calculate the applicable purchase amount rather than quoting a general premium figure.
Death Benefit, Surrender and Loan Facility
LIC New Jeevan Dhara-II also has provisions concerning death during the deferment period.
Under the single-life options, the death benefit during deferment is 105% of the total premiums paid, subject to the applicable policy conditions.
For joint-life arrangements, the death benefit is payable on the second death, as specified in the product conditions.
The plan also provides a surrender facility after two full years’ premiums have been paid under the regular-premium structure.
However, the loan facility is available only under the applicable return-of-premium options.
Customers should understand these conditions before choosing the policy, particularly when they may need access to their invested money before retirement.
LIC Health Shield (Plan 907)
LIC Health Shield is a non-participating, non-linked individual health insurance pure-risk plan. It is designed to provide financial support to families through fixed hospital cash and surgical benefits.
One important point is that LIC Health Shield is not a traditional medical claim or hospital bill reimbursement policy. It provides benefits according to the amounts and conditions specified in the policy, rather than simply reimbursing the actual hospital expenses.
The plan can cover eligible family members under one policy, making it relevant for customers looking for fixed-benefit health protection.
Key Features of LIC Health Shield
1. Daily hospital cash benefit
The policy provides a daily hospital cash benefit when the insured person meets the applicable hospitalisation conditions.
The initial daily benefit can be selected between ₹2,500 and ₹10,000 in multiples of ₹500.
2. Major surgical benefits
The plan provides a lump-sum benefit for eligible major surgeries. The major surgical benefit sum assured is calculated as 100 times the applicable daily benefit.
The actual percentage payable depends on the surgery listed in the policy annexure.
3. Family coverage
The plan allows eligible family members to be included under one policy. These include the principal insured, spouse, parents and children, subject to the applicable entry-age conditions.
4. Guaranteed premiums
The policy has a 15-year term and a 15-year premium-paying term. The premiums are guaranteed under the policy conditions.
5. No-claim benefit
Customers can receive an increase in their daily benefit after every three consecutive claim-free years.
The increase is 10% of the initial daily benefit for every qualifying three-year period.
6. Premium waiver provision
The plan also provides a premium waiver facility for eligible family members if the principal insured dies, subject to the policy conditions.
7. Critical Illness Benefit
Pays a lump sum on diagnosis of specified critical illnesses, in addition to hospital cash and surgical benefits, subject to the policy’s terms and conditions.
LIC Health Shield Eligibility and Coverage
The eligibility and coverage details are important for customers considering this plan for family protection.
| Particular | Details |
|---|---|
| Principal insured | 18–65 years |
| Spouse | 18–65 years |
| Parents | 18–65 years |
| Children | 90 days–20 years |
| Policy term | 15 years |
| Premium-paying term | 15 years |
| Initial daily benefit | ₹2,500–₹10,000 |
| Benefit selection | Multiples of ₹500 |
| Maximum daily benefit | ₹10,000 per person across policies |
| Major surgical benefit sum assured | 100 times the applicable daily benefit |
For example, if a customer selects an initial daily benefit of ₹5,000, the major surgical benefit sum assured will be ₹5 lakh. The actual amount payable for a particular surgery will depend on the applicable percentage in the policy annexure.
LIC Health Shield Premium
The following table shows the sample annual premiums for LIC Health Shield (Plan 907) for a daily benefit of ₹5,000 (excluding GST) based on the insured person’s age and gender.
| Age | Male – Yearly Premium | Female – Yearly Premium |
|---|---|---|
| 20 years | ₹6,555 | ₹5,556 |
| 30 years | ₹7,195 | ₹6,883 |
| 40 years | ₹9,446 | ₹9,509 |
| 50 years | ₹14,895 | ₹13,209 |
| 60 years | ₹22,350 | ₹17,341 |
Daily benefit: ₹5,000 · Premium frequency: Yearly
These figures are confirmed in LIC’s official Health Shield sales brochure, under Sample Premium. They apply to the Principal Insured and are illustrative annual premiums for standard lives covered under the same policy through offline purchase.
Riders Available Under LIC Health Shield
LIC Health Shield offers additional rider options to eligible policyholders.
| Rider | Purpose |
|---|---|
| LIC New Term Assurance Rider | Additional life insurance protection |
| LIC Accident Benefit Rider | Additional protection against eligible accidental events |
The total rider premium cannot exceed 30% of the base policy premium.
Customers should compare the rider benefits, eligibility conditions, and additional premium before selecting optional protection.
For agents, this product creates an opportunity to discuss fixed-benefit health protection with customers who are also exploring conventional health insurance agent commission products.
LIC New Cancer Cover (Plan 908)
LIC New Cancer Cover is a non-participating, non-linked individual health insurance pure-risk plan designed to provide financial support following an eligible cancer diagnosis.
Cancer treatment can create considerable financial pressure for families. Apart from hospital expenses, patients and their families may need financial support for other expenses and household commitments.
This policy provides fixed benefits based on the cancer stage and the sum assured selected by the policyholder.
Unlike a reimbursement-based arrangement, the benefits are determined by the policy terms rather than the actual hospital bill.
Benefits of LIC New Cancer Cover
LIC New Cancer Cover provides different benefits for early-stage and major-stage cancer.
| Cancer stage | Benefit |
|---|---|
| Early-stage cancer | 25% of the sum assured |
| Early-stage premium benefit | Future premiums waived for 3 years |
| Major-stage cancer | 100% of the sum assured as a lump sum |
| Monthly benefit after major-stage diagnosis | 1% of the sum assured every month for 10 years |
| Future premiums | Waived after an eligible major-stage diagnosis |
The benefits depend on the cancer stage and the conditions defined in the policy.
Early-stage cancer: If the insured person is diagnosed with an eligible early-stage cancer, the policy pays 25% of the sum assured. It also provides a three-year premium waiver under the applicable conditions.
Major-stage cancer: If the insured person is diagnosed with an eligible major-stage cancer, the policy pays 100% of the sum assured as a lump sum. Additionally, 1% of the sum assured is paid every month for 10 years.
The policy also waives all future premiums after an eligible major-stage diagnosis.
Example: How Much Can a Family Receive?
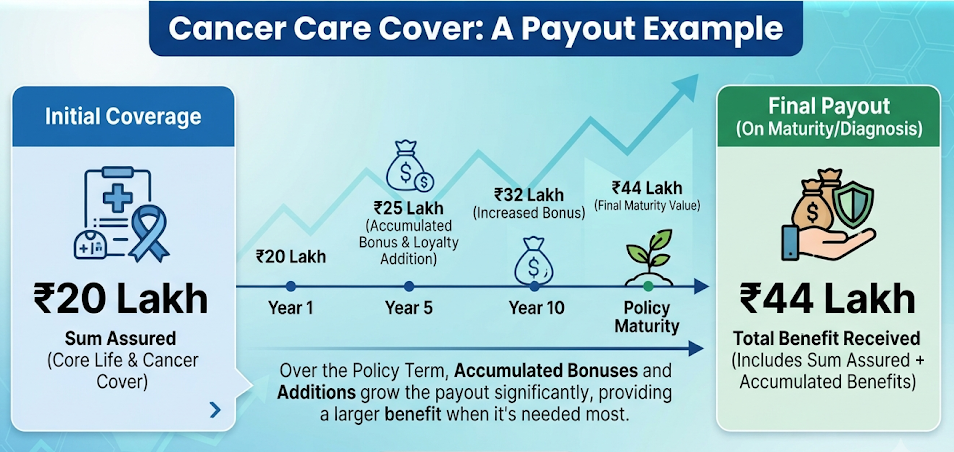
Suppose a customer purchases LIC New Cancer Cover with a sum assured of ₹20 lakh.
If the insured person receives an eligible major-stage cancer diagnosis, the benefit calculation is as follows:
| Benefit | Amount |
|---|---|
| Major-stage lump-sum benefit | ₹20,00,000 |
| Monthly benefit (1% of ₹20 lakh) | ₹20,000 |
| Monthly benefit for 10 years | ₹24,00,000 |
| Total potential benefit | ₹44,00,000 |
| Future premiums | Waived |
Therefore, the total potential benefit is ₹44 lakh, consisting of a ₹20 lakh lump sum and ₹24 lakh in monthly payments over 10 years.
This example assumes that all applicable policy conditions are satisfied.
Eligibility and Sum Assured of LIC New Cancer Cover
The plan is available to eligible individuals between 18 and 65 years of age at entry.
The maturity age ranges from 28 to 75 years, and the policy term and premium-paying term are both 10–15 years.
The minimum sum assured varies according to the customer’s age at entry.
| Entry age | Minimum sum assured |
|---|---|
| 18–34 years | ₹35 lakh |
| 35–40 years | ₹30 lakh |
| 41–50 years | ₹20 lakh |
| 51–65 years | ₹15 lakh |
The maximum sum assured is ₹50 lakh across all such policies. The sum assured is selected in multiples of ₹1 lakh.
Customers can choose between two benefit options:
- Option I – Level Sum Assured: The sum assured remains level.
- Option II – Increasing Sum Assured: The sum assured increases by 10% each year during the first five years.
The choice depends on the customer’s protection requirements and ability to pay the applicable premium.
LIC New Cancer Cover Premium
The premium depends on factors such as the insured person’s age, selected sum assured, policy term, and chosen benefit option.
The policy offers an online purchase rebate of 7.5%–10%, subject to the applicable conditions.
Agents should generate an updated illustration before providing a final quotation. Customers should also understand the exclusions and waiting-period conditions before purchasing.
Sample yearly premium for ₹50 lakh sum assured (Level option), excluding GST. Check the exact premium on licindia.in.
| Age | Male (10 yrs) | Female (10 yrs) | Male (15 yrs) | Female (15 yrs) |
|---|---|---|---|---|
| 20 | ₹4,700 | ₹5,250 | ₹4,950 | ₹6,100 |
| 35 | ₹8,050 | ₹15,200 | ₹9,100 | ₹17,600 |
| 50 | ₹25,400 | ₹37,750 | ₹32,800 | ₹41,600 |
| 60 | ₹73,050 | ₹60,500 | ₹89,150 | ₹66,750 |
Important Exclusions and Limitations
Customers should carefully read the policy exclusions before purchasing LIC New Cancer Cover.
The verified product information identifies the following conditions:
- Cancer diagnosed or treated during the 36 months before policy issuance or revival is excluded.
- A cancer diagnosis during the applicable waiting period results in termination of the policy.
- The policy does not provide a death benefit.
- There is no maturity benefit.
- There is no surrender value.
- There is no loan facility.
- There is no paid-up value.
The exact waiting-period duration and other exclusion conditions should be confirmed from the latest LIC policy brochure.
It is important to explain these limitations clearly. LIC New Cancer Cover is designed for eligible cancer-related benefits and should not be presented as a conventional savings or life insurance maturity product.
Which New LIC Plan Is Right for You?
The three LIC plans introduced in October 2026 address different financial needs. Therefore, customers should select a product according to their primary requirement rather than comparing them only on price.
| Customer requirement | Suitable plan | Why consider it? | Important limitation |
|---|---|---|---|
| Retirement income | New Jeevan Dhara-II (892) | Deferred annuity with guaranteed annuity rates | Requires understanding of deferment and annuity options |
| Family hospital protection | Health Shield (907) | Fixed hospital cash and surgical benefits | Not a hospital-bill reimbursement policy |
| Cancer-related financial protection | New Cancer Cover (908) | Lump sum and monthly benefits for eligible cancer diagnoses | No death, maturity or surrender value |
For someone planning retirement, New Jeevan Dhara-II may be worth considering.
A family looking for fixed hospital cash and surgical benefits can explore Health Shield.
An individual who wants financial protection against eligible cancer diagnoses can consider New Cancer Cover.
Customers should compare the policy conditions, eligibility, premiums, and benefits before making a final decision.
People comparing retirement products can also explore other LIC offerings, such as LIC Jeevan Labh, before making a decision.
What Do the New LIC Plans Mean for LIC Agents?
The October 2026 product launch gives LIC agents three additional products to discuss with customers. Each plan addresses a different financial concern, allowing agents to understand the customer’s needs before recommending a suitable product.
Here is how agents can position these plans during customer discussions.
1. How to Pitch LIC New Jeevan Dhara-II
New Jeevan Dhara-II can be discussed with customers who want to arrange regular retirement income.
Agents can explain the concept of deferred annuities, guaranteed annuity rates, and the available premium payment structures.
Existing LIC policyholders may be an important customer segment because the plan also provides incentives for eligible existing customers and nominees of deceased policyholders.
Agents should explain the deferment period and annuity conditions before discussing expected retirement income.
2. How to Pitch LIC Health Shield
Health Shield can be introduced to customers looking for fixed hospital cash and surgical benefits for eligible family members.
Agents should clearly explain the difference between fixed-benefit health insurance and traditional medical expense reimbursement.
Its family coverage, 15-year policy term, guaranteed premiums, and no-claim benefit are useful features to discuss during customer meetings.
3. How to Pitch LIC New Cancer Cover
New Cancer Cover can be discussed with customers concerned about the financial impact of cancer treatment.
Agents can explain the early-stage and major-stage benefits, monthly income provision and premium waiver conditions.
The policy’s exclusions and lack of maturity and death benefits must also be explained before customers make a purchase decision.
LIC Agent Commission for the New Plans
One important question agents may have is how much commission LIC pays on the three newly introduced products.
However, LIC has not published verified plan-wise commission percentages for these products in the source information used for this article.
Therefore, agents should not rely on unofficial commission figures when calculating their expected earnings.
Commission follows LIC’s current structure for annuity and health plans. Agents should check the exact applicable rate through their agent portal or the latest branch circular.
For a broader understanding of earnings, agents can refer to the LIC agent commission chart 2026.
Agents interested in professional performance targets can also learn how to qualify for MDRT.
How to Buy the New LIC Plans Online and Offline
Customers can purchase the three new LIC plans through the available LIC distribution channels.
The purchase options include:
- LIC insurance agents.
- Corporate agents.
- Insurance brokers.
- Insurance marketing firms.
- Online purchase through the official LIC website.
Customers interested in purchasing directly can visit licindia.in to check the latest product information and online purchasing facilities.
Before purchasing, customers should review the policy brochure, eligibility conditions, premium quotation, benefits and exclusions.
For New Cancer Cover, eligible online buyers can also check the applicable online purchase rebate.
Those who prefer offline assistance can contact an LIC agent to understand the product conditions and obtain a personalised illustration.
Other LIC Plans Launched in 2026
The three October 2026 products are not the only new LIC launches this year.
These products were announced through LIC’s September 2026 press release on LIC Bima Platinum and Jeevan Raksha.
- LIC Bima Platinum (Plan 770): Introduced on 1 September 2026.
- LIC Jeevan Raksha (Plan 894): Introduced on 1 September 2026.
These launches expand LIC’s product portfolio for 2026.
Customers interested in exploring LIC’s wider product portfolio can also compare products such as LIC Bima Kiran according to their financial needs and eligibility.
Final Words:
The three new LIC plans launched in October 2026 address three different financial requirements: retirement income, family hospital protection, and cancer-related financial security.
LIC New Jeevan Dhara-II focuses on deferred annuity income, Health Shield provides fixed hospital cash and surgical benefits, and New Cancer Cover offers financial support for eligible cancer diagnoses.
For LIC agents, these launches create additional opportunities to discuss retirement and health protection with customers. However, understanding the eligibility conditions, benefits, exclusions, and applicable commission structure is essential before recommending any product.
Customers should always refer to the latest official LIC brochures and policy documents before making a purchase decision.
FAQs:
Q. Which new plans did LIC launch in October 2026?
A. LIC’s New Jeevan Dhara-II (Plan 892), LIC’s Health Shield (Plan 907) and LIC’s New Cancer Cover (Plan 908), on sale from 19 October 2026.
Q. What is LIC Health Shield 907?
A. A 15-year family health plan that pays fixed hospital cash per day plus lump sums for major surgeries and critical illnesses. It is not a reimbursement (mediclaim) policy.
Q. How much does LIC New Cancer Cover pay?
A. Premiums are waived for 3 years after early-stage cancer, and all future premiums are waived after major-stage cancer.
Q. What is the minimum sum assured in LIC New Cancer Cover?
A. ₹15 lakh to ₹35 lakh depending on age (younger buyers need higher cover); maximum ₹50 lakh.
Q. Is LIC New Jeevan Dhara-II a pension plan?
A. Yes – it is a deferred annuity plan. You pay for 1-15 years and then get a guaranteed income for life.
Q. Can I buy these plans online?
A. Yes, at licindia.in or through an LIC agent. Buying New Cancer Cover online gives a premium rebate.
Q. Who can be covered under Health Shield?
A. The principal insured, spouse, and parents aged 18-65, and children from 90 days to 20 years.
Q. Does New Cancer Cover give money back at maturity?
A. No. It is a pure protection plan – there is no maturity, death or surrender benefit.
Sources and Further Reading
The following sources were identified in the verified research brief:
- LIC Press Release – Introduction of Three New Plans (13 October 2026)
- LIC Official Website
- LIC New Jeevan Dhara-II – Product Information
- LIC Health Shield – Product Information
- LIC New Cancer Cover – Product Information
- LIC Bima Platinum and Jeevan Raksha – September 2026 Announcement
- Business Today report